Is a Hit and Run Considered a Comprehensive Claim
A hit and run is usually paid under your uninsured motorist or collision coverage, not comprehensive, because another car caused the damage.
What decides which coverage pays for a hit and run
- Not a comprehensive event Comprehensive covers things like weather, animals, and theft, not crashes caused by another driver. A hit and run almost always involves impact from another vehicle, so it falls outside that category.
- Uninsured motorist coverage Most policies treat a fleeing driver as an unidentified uninsured motorist. If you carry uninsured motorist property damage or collision coverage, that's typically what pays.
- Collision coverage as a backup If you don't have uninsured motorist property damage, your collision coverage can pay for the damage instead. You'll still owe your collision deductible unless your state or insurer waives it for hit and run claims.
- State rules vary widely Some states require insurers to waive the deductible for hit and run claims, others don't. Check your policy or ask your insurer directly which coverage applies and whether any deductible is reduced.
- A police report matters Insurers usually want a police report to confirm the other driver fled and couldn't be identified. File one quickly, since delays can make the claim harder to support.
A parked car hit while the owner was inside a store
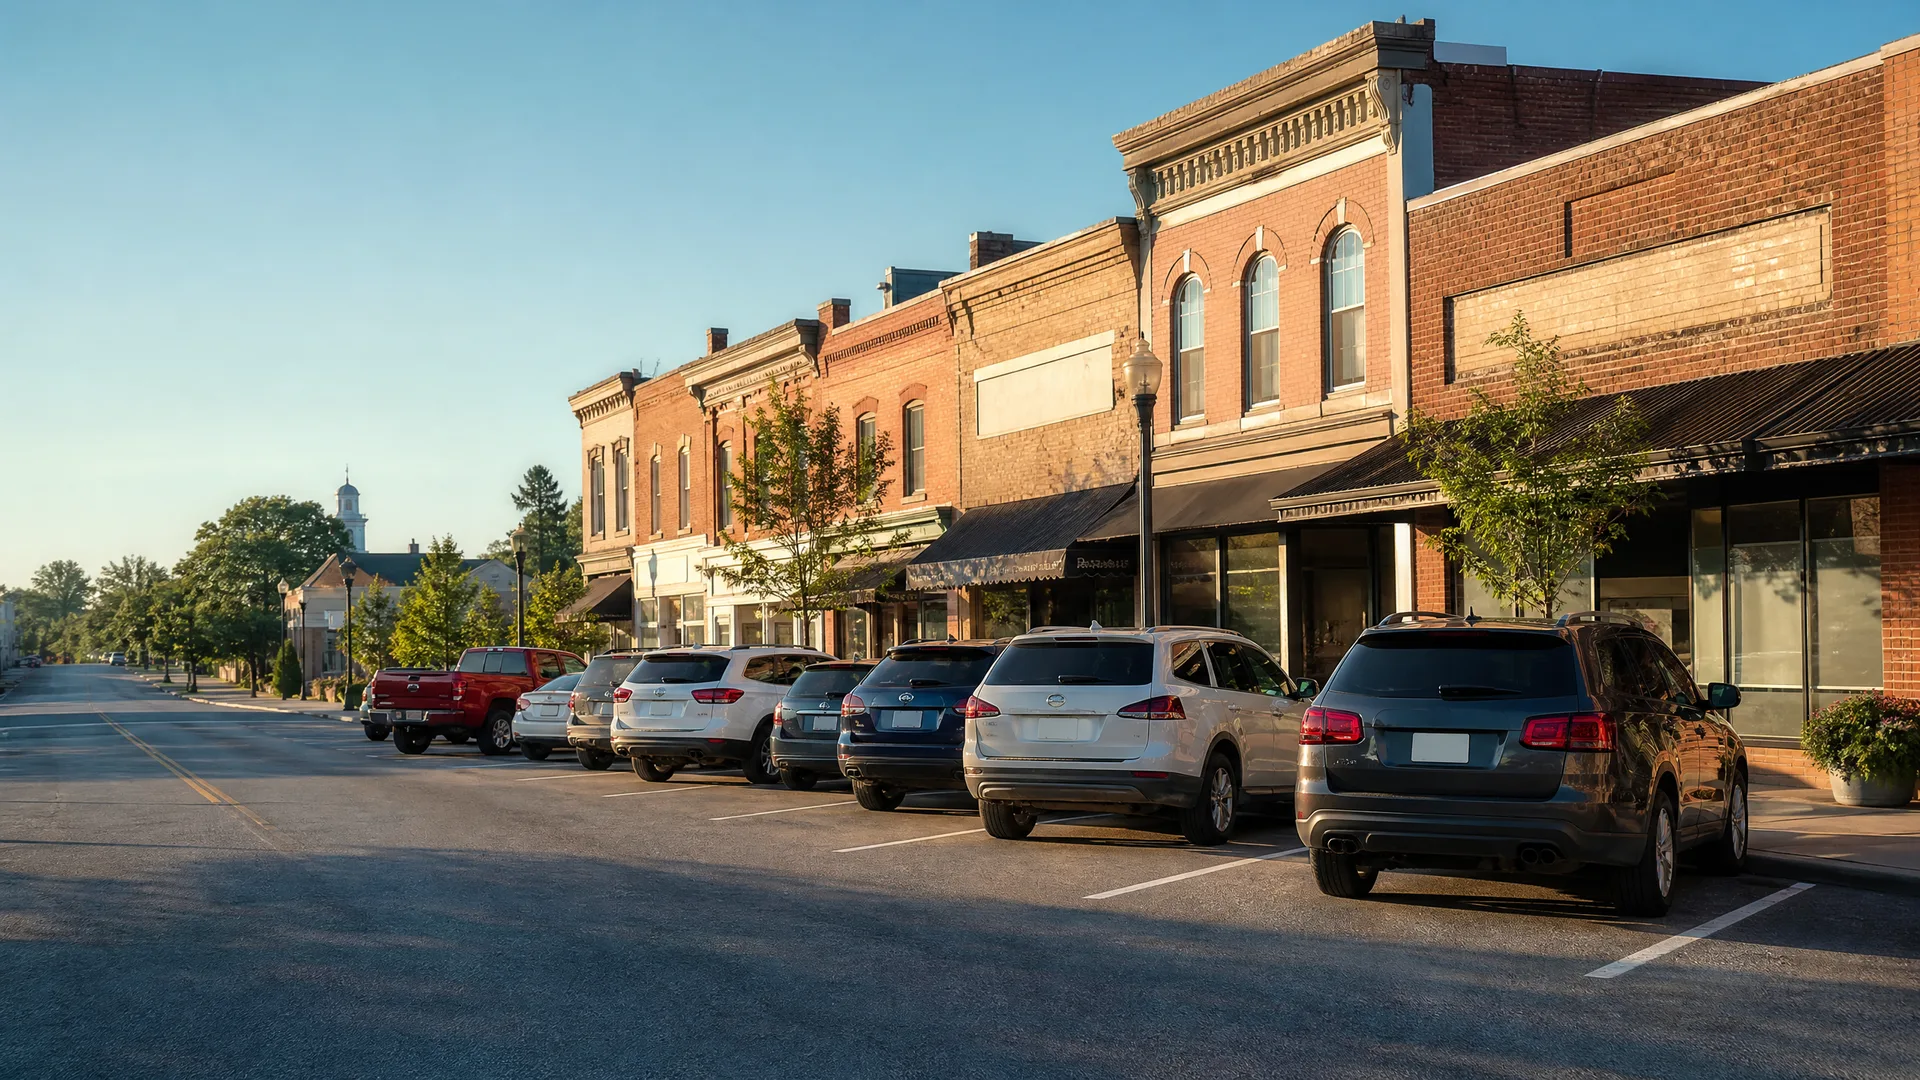
Someone backed into a parked car in a lot and drove off without leaving information. The owner came out, saw the damage, and had no way to identify the other driver. They called the police to file a report and then called their insurer the same day.
The insurer asked whether the policy included uninsured motorist property damage coverage. It did, so the claim was handled under that coverage rather than comprehensive, and no deductible applied because the state required a waiver for hit and run claims. If the owner hadn't had that coverage, the repair would have gone through collision coverage instead, with the regular deductible applying. The car was fixed within two weeks, and the owner's rates were not affected since they weren't at fault.
Compare quotes now that you know which coverage actually pays for a hit and run.
Why hit and run claims work this way
Comprehensive coverage exists for damage that doesn't come from a collision with another vehicle or object, things like fire, flooding, or a falling tree. A hit and run, by definition, involves a crash, so insurers classify it as a collision-type event even though you didn't cause it and can't identify who did.
The reason uninsured motorist coverage often takes over is that the law in most states treats an unidentified driver the same as one with no insurance. You can't collect from someone you can't find, so your own uninsured motorist coverage, if you have it, steps in to cover what that driver would have owed you. This is why having that coverage matters even if you think you'll never need it.
Without uninsured motorist property damage coverage, your collision coverage is the fallback, since it covers damage from any collision regardless of fault. The tradeoff is that collision claims usually carry a deductible, while hit and run claims under uninsured motorist coverage sometimes don't, depending on where you live.
The cases where this gets complicated involve shared fault or unclear facts, like a crash where it's not obvious who hit whom first. Insurers investigate these more closely, and the outcome can depend on witnesses, damage patterns, or security footage. That's a separate question from which coverage type applies, but it can affect how smoothly the claim moves.
The coverage that protects you from a hit and run is the one you chose before it happened, not comprehensive.
Does filing a hit and run claim raise my insurance rates?
Usually not, because you weren't at fault for the accident. Insurers generally don't penalize you for claims where another driver caused the damage and fled. Some insurers may still consider the claim history when pricing future policies, so ask directly if you're concerned. This can vary by insurer and by state, so check your policy's rate protection terms.
What if I don't have uninsured motorist property damage coverage?
Your collision coverage would likely pay instead, if you carry it. You'd pay your collision deductible, and the claim would count as a collision claim rather than an uninsured motorist claim. If you have neither coverage, you'd likely have to pay for repairs yourself, so it's worth checking your policy now rather than after an accident.
Can I still file a claim if I never find the other driver?
Yes, you don't need to identify the other driver to file a hit and run claim. You do need a police report and enough evidence that a collision occurred and the other driver left the scene. Insurers may ask for photos, witness statements, or damage consistent with another vehicle to support the claim.